
Published · Updated
examples of capital structuresCapital structure examples for UK property developers 2026
By James Dawes, CeMAP, Founder, James William & Co Capital
Choosing the right capital structure for a UK property development project has become increasingly challenging in 2026. Rising interest rates, evolving tax regulations, and the need for sophisticated funding arrangements mean developers must carefully consider how they finance each deal. Senior debt, mezzanine finance, preferred equity, developer equity, and family investment companies all play distinct roles in the capital stack. This article provides practical examples and expert insights to help high-net-worth investors and developers structure their projects effectively, balancing cost, risk, control, and tax efficiency across complex real estate transactions.
Table of Contents
- Criteria For Choosing Capital Structures In UK Property Development
- Key Examples Of Capital Structure Components For UK Property Developers
- Comparing Capital Structures: Benefits And Limitations For UK Property Projects
- Making The Right Capital Structure Decision For Complex UK Real Estate Deals
- Specialist Property Finance Solutions From James William & Co Capital
- Frequently Asked Questions
Key takeaways
| Point | Details |
|---|---|
| Senior debt dominance | Senior debt typically funds 60-70% of UK property development projects, offering the lowest cost and first-priority security. |
| Mezzanine and preferred equity | These intermediate layers contribute 10-20% of funding, bridging the gap between senior debt and equity at moderate cost. |
| Developer equity stake | Developer equity usually accounts for 10-20% of total project cost, aligning incentives and demonstrating commitment. |
| Family investment companies | FICs suit families with assets over £2 million, enabling wealth transfer whilst retaining control and tax planning benefits. |
| Capital stack positioning | Moving up the capital stack increases funding cost due to higher risk, requiring careful optimisation for each project. |
Criteria for choosing capital structures in UK property development
Selecting the optimal capital structure for a property development project requires a clear understanding of several critical factors. Your risk appetite fundamentally shapes the debt-to-equity ratio you choose. Conservative developers favour higher senior debt proportions, accepting stricter covenants in exchange for lower interest rates. Aggressive investors might leverage mezzanine finance or preferred equity to maximise returns, accepting higher costs for greater flexibility. Structuring the right mix of funding is crucial for property development in the UK, particularly when balancing multiple stakeholder interests.
Tax and inheritance considerations represent another vital dimension. High-net-worth individuals often weigh family investment companies against traditional trusts or direct ownership structures. FICs offer specific advantages for inheritance tax planning, allowing you to gift shares to beneficiaries whilst retaining voting control through alphabet shares. However, asset transfers into FICs can trigger capital gains tax and stamp duty land tax liabilities that must be carefully modelled. Understanding how to optimise real estate funding within your broader wealth strategy becomes essential when projects exceed £2 million in value.
Control preferences and profit extraction methods also influence capital structure decisions. If you prioritise operational control and decision-making authority, you will want to minimise dilutive equity investors and maintain a higher proportion of senior debt. Conversely, if you seek strategic partners who bring expertise alongside capital, preferred equity or joint venture structures may prove attractive. The way you intend to extract profits matters too. Dividend distributions, loan repayments, and capital gains each carry different tax treatments under UK law. Your choice of capital structure should align with your preferred exit strategy and cash flow requirements throughout the development lifecycle.
Pro Tip: Always model multiple capital structure scenarios with your tax adviser before committing to a funding arrangement. Small changes in the debt-to-equity mix can produce significant differences in your after-tax returns, particularly when considering corporation tax relief on interest payments versus dividend taxation on equity returns.
Funding cost represents perhaps the most tangible selection criterion. Senior debt commands the lowest interest rates because it sits first in the repayment waterfall, typically ranging from 6% to 9% per annum in 2026 for UK development projects. Mezzanine finance and preferred equity sit higher in the capital stack, with returns often reaching 12% to 18% annually. Developer equity bears the highest risk and therefore requires the highest return, though this return is realised through profit share rather than fixed interest. You must balance the weighted average cost of capital against the risk profile of your specific project.
Project complexity and required flexibility round out the key criteria. Large-scale, multi-phase developments benefit from flexible capital structures that allow staged drawdowns and varied repayment terms. Smaller, single-phase projects might suit simpler senior debt arrangements with straightforward term structures. If your project involves planning risk, contamination issues, or uncertain sales absorption, you need funding partners who understand these complexities and can structure covenant packages accordingly. The real estate debt landscape in the UK offers diverse options, but matching the right funding type to your project’s specific risk profile requires careful analysis.
Key examples of capital structure components for UK property developers
Senior debt forms the foundation of most UK property development capital structures. This first-ranking debt typically covers 60-70% of total project costs, secured by a first charge over the development site and any completed units. Banks, specialist development lenders, and debt funds provide senior debt with interest rates ranging from 6% to 9% per annum in 2026. The relatively low cost reflects the lender’s priority position in the capital stack. If the project encounters difficulties, senior lenders recover their capital before any other funders receive repayment. Loan-to-value ratios, interest cover covenants, and minimum equity requirements form the core terms you will negotiate.
Mezzanine finance or preferred equity often contributes 10-20% of the funding, sitting between senior debt and developer equity in the capital stack. Mezzanine lenders accept second-ranking security, meaning they only receive repayment after senior debt obligations are satisfied. This subordinated position justifies higher returns, typically 12% to 18% per annum. Preferred equity functions similarly but structures returns as profit share rather than interest payments, which can offer tax advantages in certain circumstances. Both instruments provide crucial flexibility when senior debt alone cannot reach the required loan-to-cost ratio. Understanding the full range of real estate funding sources available helps you identify when mezzanine or preferred equity makes commercial sense.
Developer equity typically accounts for 10-20% of the total project cost, representing your own capital contribution to the development. This equity demonstrates your commitment to the project and aligns your interests with those of debt providers. Lenders view substantial developer equity as a strong indicator of project viability and your confidence in the business plan. Your equity sits at the bottom of the capital stack, bearing the highest risk. If the project underperforms, you absorb losses before any debt providers suffer impairment. However, this risk position also entitles you to the residual profits after all debt obligations are satisfied, creating the potential for outsized returns on successful projects.
Family investment companies offer high-net-worth families a tax-efficient vehicle for holding and developing property assets whilst planning wealth transfer to the next generation. The structure allows parents to retain control through voting shares whilst gifting growth shares to children, potentially reducing inheritance tax exposure over time.
Family Investment Companies are often considered where assets are around £2 million or more, making them particularly relevant for substantial development portfolios. Unlike trusts, FICs operate as standard limited companies, providing transparency and flexibility in governance. You can structure share classes to separate voting rights from economic interests, maintaining operational control whilst facilitating wealth transfer. Dividends paid to family members are subject to income tax, and the company pays corporation tax on profits, creating different tax dynamics compared to direct ownership or trust structures.
Legal and tax implications require careful consideration when establishing any capital structure component. Asset transfers into FICs or other corporate vehicles can trigger capital gains tax if you transfer property at market value rather than cash. Stamp duty land tax applies to property transfers at rates up to 15% for high-value residential properties acquired by companies. HMRC treats non-cash contributions at current market value, potentially crystallising tax liabilities that erode the benefits of the structure. You must model these costs against the long-term inheritance tax savings and operational benefits before proceeding. Working with specialists who understand both property development finance and wealth structuring ensures you avoid costly mistakes in the initial setup phase.
Comparing capital structures: benefits and limitations for UK property projects
Each capital structure component carries distinct characteristics that make it suitable for different project scenarios and investor objectives. The following comparison helps you evaluate which combination best serves your specific development.
| Component | Typical % | Annual Cost | Risk Level | Control | Tax Treatment |
|---|---|---|---|---|---|
| Senior debt | 60-70% | 6-9% | Lowest | Limited | Interest deductible |
| Mezzanine finance | 10-20% | 12-18% | Moderate | Moderate | Interest deductible |
| Preferred equity | 10-20% | 12-18% | Moderate-High | Moderate | Profit share, no deduction |
| Developer equity | 10-20% | Variable | Highest | Full | Subject to CGT on exit |
| Family Investment Company | Structure dependent | Variable | Variable | Tailored | Corporation tax, IHT planning |
Senior debt delivers the lowest cost of capital but imposes the strictest covenants and reporting requirements. You will face regular valuations, drawdown conditions tied to construction milestones, and potentially personal guarantees depending on your track record. The limited control extends to major decisions. Most senior debt facilities require lender consent for significant contract variations, sales strategy changes, or additional borrowing. However, the interest payments reduce your taxable profit, providing valuable tax relief that improves overall returns. For established developers with strong cash flows and conservative leverage targets, senior debt forms an efficient base layer.
Mezzanine finance occupies the middle ground, offering greater flexibility than senior debt whilst maintaining some security through second-ranking charges. As you move up the capital stack, the cost of money increases due to higher risk, but you gain operational freedom. Mezzanine lenders typically impose fewer operational covenants, focusing instead on financial performance metrics and exit timelines. The interest remains tax-deductible, though the higher rate reduces the benefit. Mezzanine works well when you need to bridge a funding gap but want to preserve equity upside. Understanding the various types of property finance helps you determine when mezzanine provides the optimal balance.
Pro Tip: When comparing mezzanine finance and preferred equity, model the after-tax cost carefully. Mezzanine interest is deductible, reducing your effective cost by your marginal corporation tax rate. Preferred equity distributions are not deductible, but they may offer more flexible payment terms during the construction phase when cash flow is tight.
Developer equity grants you complete control over project decisions and entitles you to all residual profits after debt obligations are satisfied. The risk is substantial. If the project fails, you lose your entire equity investment before any lender suffers a loss. However, successful projects can generate returns exceeding 20% per annum on your equity contribution. Capital gains tax applies when you realise profits, currently at rates up to 20% for higher-rate taxpayers on property disposals. The lack of ongoing interest payments improves cash flow during construction, though you must fund this equity from personal resources or other investments.
Compared with trusts, Family Investment Companies involve different inheritance tax, income tax, and capital gains considerations that require specialist advice. FICs offer superior control through tailored share structures, allowing you to retain decision-making authority whilst gradually transferring economic value to beneficiaries. The company structure provides transparency that trusts cannot match, with clear accounts and defined ownership percentages. However, the setup and ongoing administration costs exceed those of simpler structures. You must weigh these costs against the inheritance tax planning benefits and operational flexibility that FICs deliver for high-value portfolios.
Capital stack positioning fundamentally affects both cost and investor appetite for your project. Senior lenders seek secure, predictable returns and prioritise capital preservation. They will lend against conservative valuations and require robust downside protection. Mezzanine and preferred equity investors target higher returns commensurate with their subordinated position, often bringing sector expertise and strategic value beyond pure capital. Your equity position aligns your interests with all funders whilst capturing the upside potential. Engaging capital advisory specialists helps you structure the optimal stack for your specific project characteristics and risk profile.
Making the right capital structure decision for complex UK real estate deals
Matching your capital structure to project characteristics and personal objectives requires a systematic approach. For lower-risk projects with strong pre-sales or forward funding commitments, you can confidently pursue senior debt-dominant structures. A typical arrangement might comprise 70% senior debt, 15% mezzanine finance, and 15% developer equity. This configuration minimises your equity requirement whilst maintaining acceptable leverage ratios for senior lenders. The predictable cash flows from pre-sold units or forward purchase agreements provide comfort to debt providers, allowing you to negotiate favourable terms. Large-scale residential schemes with established demand profiles suit this approach particularly well.
Higher-risk projects with planning uncertainty, contamination issues, or speculative elements demand more equity-heavy structures. You might structure 60% senior debt, 10% mezzanine, and 30% developer equity to provide adequate cushion for lenders. The increased equity demonstrates your confidence and provides a larger buffer against cost overruns or market downturns. Alternatively, you could introduce a joint venture partner who contributes equity alongside you, sharing both risk and returns. This approach works well for complex urban regeneration projects where specialist expertise adds value beyond pure capital contribution. Reviewing property development funding tips specific to high-risk scenarios helps you structure appropriately.
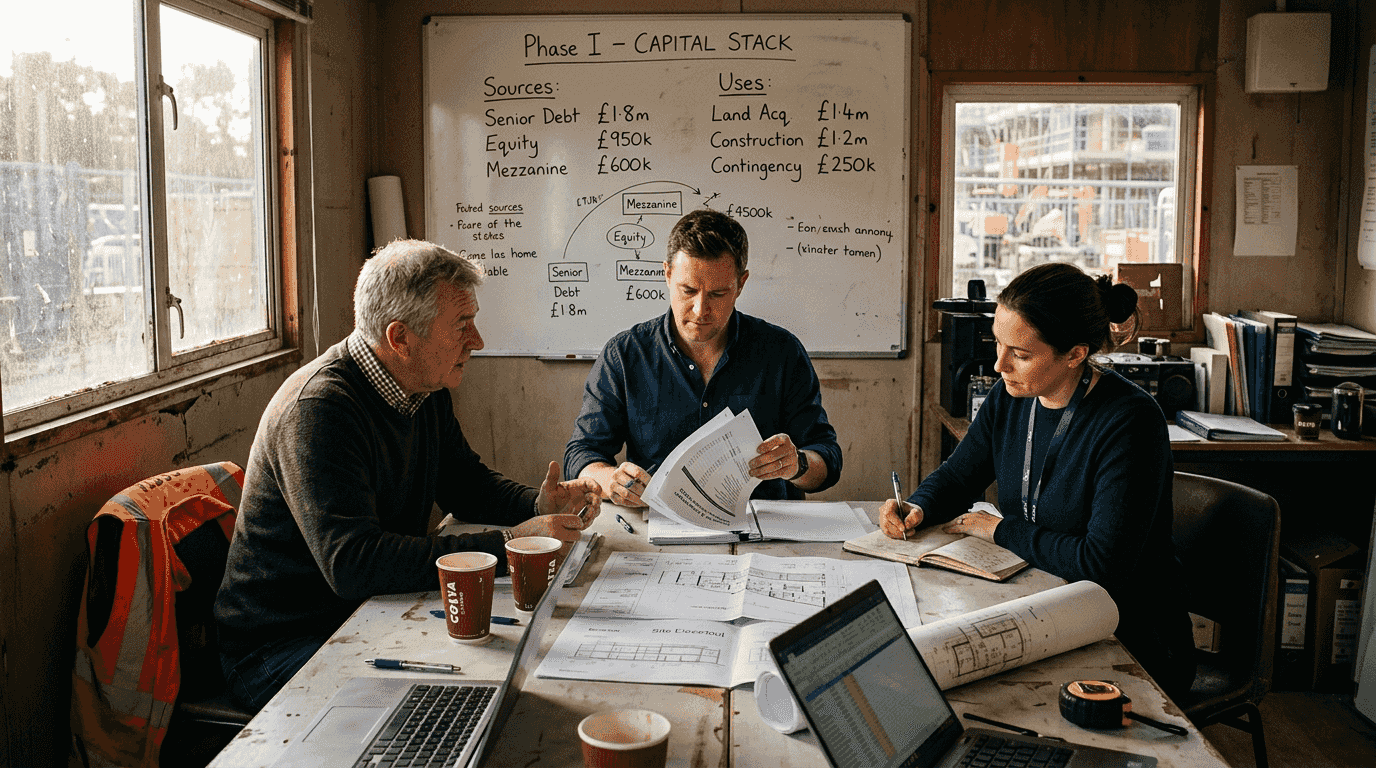
Mezzanine finance and preferred equity serve crucial roles in bridging funding gaps when senior debt alone cannot reach the required loan-to-cost ratio. Consider a scenario where senior lenders will only advance 65% loan-to-cost, but you want to limit your equity to 15%. A 20% mezzanine facility bridges the gap, allowing the project to proceed without excessive equity dilution. The higher cost of mezzanine is often justified by the leverage benefit and the ability to deploy your equity across multiple projects rather than concentrating it in a single development. This strategy suits experienced developers with proven track records who can access mezzanine finance on reasonable terms.
Pro Tip: When structuring mezzanine or preferred equity, negotiate intercreditor terms carefully. The relationship between senior and mezzanine lenders significantly affects your operational flexibility. Ensure the intercreditor agreement allows reasonable flexibility for contract variations and sales strategy adjustments without requiring consent from multiple parties.
Developer equity contributions align incentives across the capital stack and signal your commitment to project success. Lenders view substantial developer equity as essential risk mitigation, particularly for first-time developers or untested markets. Beyond the minimum equity required by lenders, consider whether additional equity improves your overall returns by reducing expensive mezzanine layers. If you have available capital earning modest returns in other investments, redeploying it as development equity might generate superior risk-adjusted returns. However, concentration risk becomes a concern. Spreading equity across multiple smaller projects often provides better risk management than concentrating everything in one large development.
Family Investment Companies may be suitable for families with substantial assets who want to pass on wealth while retaining control, particularly when your development portfolio exceeds the £2 million threshold. The FIC can hold multiple development projects, providing a corporate vehicle that simplifies financing arrangements and creates clear succession planning. You gift growth shares to children or grandchildren whilst retaining voting shares, ensuring you maintain operational control during your lifetime. The company structure allows you to pay salaries to family members involved in the business, creating income-splitting opportunities. However, you must consult tax and legal experts to navigate capital gains tax and stamp duty land tax implications when transferring existing properties into the FIC structure. Understanding how to structure development finance within a FIC framework requires specialist knowledge of both property and wealth planning disciplines.
Specialist property finance solutions from James William & Co Capital
Navigating the complexities of capital structures for UK property development requires expertise across multiple funding sources and structuring techniques. James William & Co Capital specialises in arranging sophisticated funding for large-scale acquisitions, ground-up developments, and complex refinances. Our capital concierge approach provides you with a single point of contact for structuring multi-layered debt stacks, negotiating with senior lenders, arranging mezzanine finance, and coordinating equity partners.

We work with a network of family offices, private credit funds, and specialist lenders to deliver rapid, tailored solutions for high-value real estate transactions. Whether you need to optimise your capital structure for tax efficiency, bridge a funding gap with mezzanine finance, or establish a family investment company for wealth planning, our team brings deep expertise in UK structured property finance. Explore our specialist property finance services, review detailed case studies of complex transactions we have structured, or discover the full range of property finance services available to professional developers and high-net-worth investors in 2026.
Frequently asked questions
What is a capital structure in property development?
A capital structure represents the mix of debt and equity financing used to fund a property development project. Senior debt sits at the bottom of the risk hierarchy with first claim on assets, whilst equity sits at the top bearing the highest risk but capturing residual profits. The optimal structure balances cost, risk, control, and tax efficiency based on project characteristics and investor objectives.
How much senior debt is typical in UK property development?
Senior debt typically covers 60-70% of total project costs in UK property development, secured by a first charge over the site and completed units. This proportion provides the foundation of most capital structures, offering the lowest cost of funding due to the lender’s priority position in the repayment waterfall. Loan-to-value ratios, interest cover covenants, and developer equity requirements determine the exact percentage available for each project.
What are family investment companies and when are they appropriate?
Family Investment Companies are often considered where assets are around £2 million or more, providing a corporate structure for holding property investments whilst planning wealth transfer. They enable parents to gift growth shares to children whilst retaining voting control, potentially reducing inheritance tax exposure over time. FICs suit families seeking transparency, operational control, and tax-efficient succession planning for substantial property portfolios.
What tax issues arise from capital contributions in property finance?
Asset transfers other than cash can trigger CGT and SDLT as they are treated at market value by HMRC, potentially creating significant tax liabilities when establishing corporate structures. Property transfers into family investment companies or other vehicles crystallise capital gains based on current market values, whilst stamp duty land tax applies at rates up to 15% for high-value residential properties acquired by companies. Careful tax planning with specialist advisers is essential before implementing any capital structure involving asset transfers.
Recommended
Related Topics
Speak to a specialist
Discuss your finance with James directly
Whole-of-market specialist finance — bridging, development, commercial and residential. No call centres, no obligation. James reviews every enquiry personally.
New to specialist finance? How unbiased broker advice works · Deals we have completed
Explore Related Finance