
Published · Updated
what is bespoke fundingWhat is bespoke funding? Tailored property finance UK
By James Dawes, CeMAP, Founder, James William & Co Capital
Bespoke funding often gets mistaken for a standard loan product, yet it represents something fundamentally different. For UK high-net-worth individuals and institutional investors pursuing complex property acquisitions or large-scale developments, bespoke funding delivers customised capital structures that traditional lenders simply cannot accommodate. This guide clarifies what bespoke funding truly involves, its strategic advantages for sophisticated property projects, and practical steps to access these tailored solutions in the UK market.
Table of Contents
- Understanding Bespoke Funding In UK Property Finance
- Why Bespoke Funding Matters For High-Net-Worth Individuals And Institutional Investors
- Comparing Bespoke Funding With Traditional Property Finance Products
- How To Secure Bespoke Funding For Your Property Investment In The UK
- Discover Tailored Property Finance Solutions With James William & Co Capital
- What Is Bespoke Funding? Frequently Asked Questions
Key takeaways
| Point | Details |
|---|---|
| Bespoke funding definition | Customised property finance crafted to match unique project requirements and investor objectives |
| Primary beneficiaries | High-net-worth individuals and institutions managing complex, large-scale UK property deals |
| Key distinction | Offers flexible structures, tailored covenants and bespoke pricing versus rigid traditional lending |
| Current market context | Bank of England base rate at 4% influences bespoke funding costs and availability |
| Access pathway | Engage specialist advisers early, prepare comprehensive documentation, negotiate flexible terms |
Understanding bespoke funding in UK property finance
Bespoke funding represents customised financing engineered specifically for the unique demands of large or complex property transactions. Unlike standard lending products that impose rigid criteria and fixed structures, bespoke funding adapts to the project’s cashflow patterns, timelines and risk profile. This distinction matters enormously when you’re managing multi-phase developments, mixed-use acquisitions or projects involving offshore structures.
Traditional lenders typically offer standardised products with predetermined loan-to-value ratios, fixed repayment schedules and inflexible covenant packages. Bespoke funding breaks this mould entirely. It involves detailed negotiation to craft loan structures, repayment terms, security arrangements and pricing that align precisely with your project’s financial architecture. The current UK lending environment, with the base rate at 4% going into late 2025, shapes both cost and availability of bespoke solutions.
Key characteristics that define bespoke funding include:
- Flexible loan structures accommodating irregular cashflows or phased drawdowns
- Custom covenant packages tailored to operational realities rather than generic templates
- Bespoke collateral arrangements accepting diverse security types beyond standard property charges
- Negotiated pricing reflecting actual project risk rather than formulaic rate cards
- Adaptable repayment profiles matching project exit strategies and cashflow generation
- Relationship-driven approach enabling ongoing term adjustments as circumstances evolve
For sophisticated investors pursuing real estate funding optimisation, bespoke funding provides the structural flexibility that complex projects demand. This tailored approach proves particularly valuable when standard lending criteria would either decline the opportunity entirely or impose terms that undermine project viability.
Why bespoke funding matters for high-net-worth individuals and institutional investors
Bespoke funding addresses specific challenges that high-net-worth individuals and institutions face when financing sophisticated property ventures. Standard banks often cannot accommodate deal structures involving multiple phases, mixed-use elements, offshore vehicles or unconventional security arrangements. Bespoke solutions fill this gap by engineering financing that works with your project architecture rather than against it.
The strategic benefits extend beyond simple approval. Bespoke funding optimises capital deployment for projects with extended timelines or irregular cashflows, situations where rigid repayment schedules create unnecessary pressure. It also enables more competitive pricing through negotiated terms that accurately reflect project-specific risk rather than broad-brush categorisations. With inflation cooling to approximately 3.8% in mid-2025, the cost environment for tailored financing has become more predictable.
Top five benefits bespoke funding delivers:
- Structural flexibility accommodating complex deal architectures that standard products cannot support
- Project customisation aligning financing terms precisely with development phases and cashflow patterns
- Capital efficiency optimising leverage and preserving equity through tailored loan-to-value arrangements
- Risk management reducing operational constraints via bespoke covenants and reporting requirements
- Relationship-driven service providing ongoing support and term flexibility as projects evolve
These advantages prove particularly valuable for property development funding where standard lending often imposes constraints that compromise project economics. Bespoke funding aligns the capital structure with your investment thesis rather than forcing compromises.
Pro Tip: Engaging specialists experienced in bespoke deals early prevents common pitfalls such as accepting inflexible terms or paying unnecessarily high costs due to poor structuring.
Comparing bespoke funding with traditional property finance products
Understanding the practical differences between bespoke funding and traditional property finance clarifies when each approach suits your needs. Traditional lending operates through standardised products with fixed eligibility criteria, predetermined loan-to-value ratios and formulaic approval processes. Bespoke funding inverts this model, starting with your project requirements and engineering financing around them.
The approval process differs fundamentally. Traditional lenders assess applications against rigid scorecards and product criteria, often declining opportunities that fall outside narrow parameters. Bespoke funding providers take a consultative approach, examining project fundamentals and structuring terms that accommodate unique circumstances. This relationship-driven methodology enables solutions for complex situations that automated underwriting would reject.
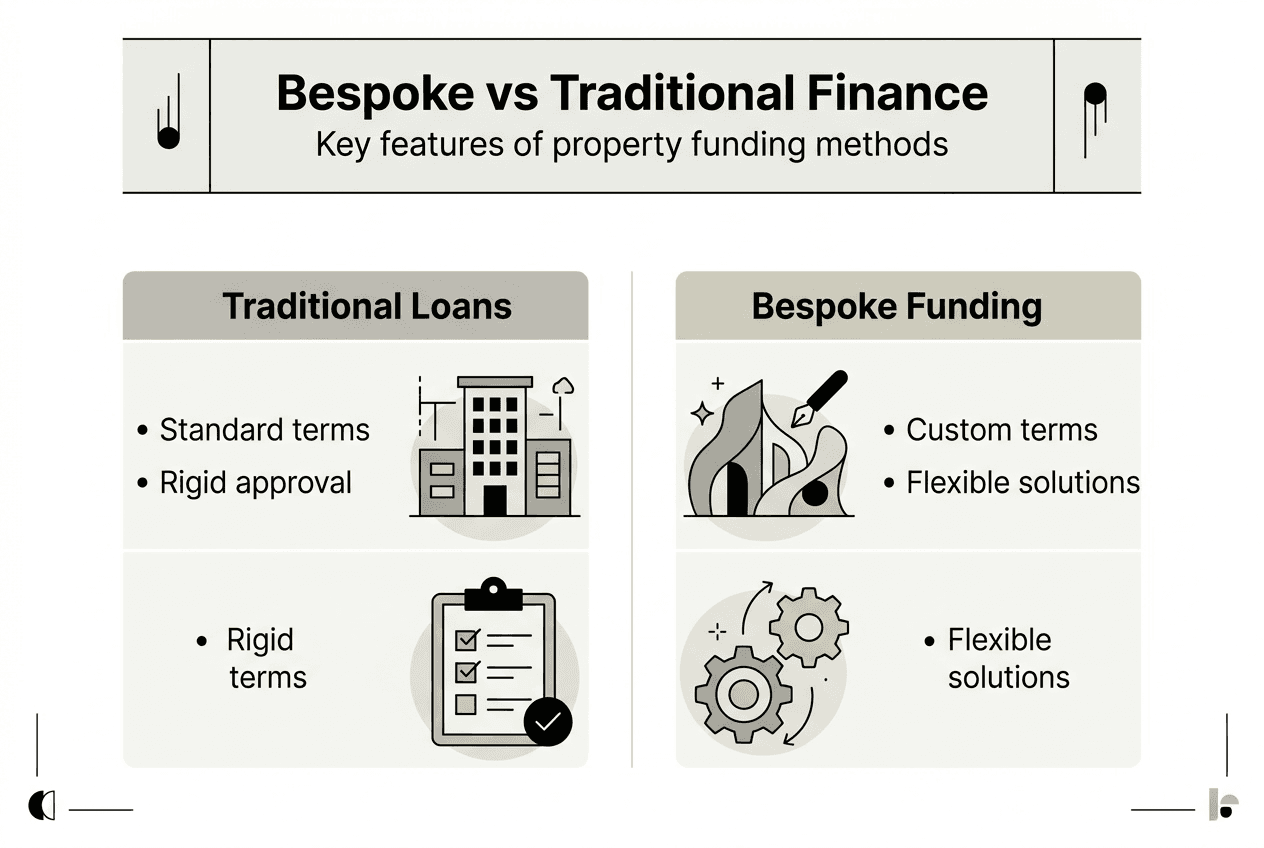
| Aspect | Traditional Property Finance | Bespoke Funding |
|---|---|---|
| Purpose | Standardised residential or commercial mortgages | Customised solutions for complex projects |
| Flexibility | Fixed terms, rigid criteria | Tailored structures, negotiable terms |
| Term length | Predetermined periods | Aligned with project timelines |
| Interest rates | Product rate cards | Negotiated based on project risk |
| Security | Standard property charges | Flexible collateral arrangements |
| Approval time | 4-8 weeks typical | Variable, often faster for established relationships |
| Typical users | Individual buyers, small investors | High-net-worth individuals, institutions, developers |
With the base rate at 4%, both traditional and bespoke funding costs reflect current monetary policy, yet bespoke solutions offer greater scope for pricing negotiation.
Key advantages and limitations for large-scale property investors:
- Traditional finance pros: Predictable terms, straightforward documentation, competitive rates for standard scenarios
- Traditional finance cons: Rigid criteria exclude complex projects, inflexible covenants, limited structural adaptation
- Bespoke funding pros: Accommodates complex structures, tailored risk assessment, flexible terms, relationship-driven support
- Bespoke funding cons: Requires more detailed documentation, potentially higher initial costs, relationship-dependent
For sophisticated investors exploring types of property finance, bespoke funding becomes essential when project complexity exceeds what standardised products can accommodate. The choice depends on whether your transaction fits traditional lending parameters or requires custom engineering.
How to secure bespoke funding for your property investment in the UK
Accessing bespoke funding successfully requires strategic preparation and expert guidance. The process differs substantially from standard mortgage applications, demanding comprehensive project documentation and skilled negotiation to secure optimal terms. Following a structured approach maximises your chances of securing favourable financing.
-
Define project requirements precisely: Document your financing needs including amount, term, drawdown profile, repayment structure and any special requirements such as offshore vehicles or phased releases. Clarity on these fundamentals enables advisers to identify suitable lenders and structure appropriate proposals.
-
Engage specialist capital advisers: Work with professionals experienced in bespoke funding who maintain relationships with family offices, private credit funds and specialist lenders. Their market knowledge and negotiating expertise prove invaluable in securing competitive terms and navigating complex structuring.
-
Prepare comprehensive documentation: Assemble detailed project feasibility studies, cashflow projections, asset valuations, security details and sponsor background information. Bespoke lenders conduct thorough due diligence, so comprehensive preparation accelerates approval and demonstrates professionalism.
-
Negotiate flexible terms strategically: Focus discussions on repayment flexibility, covenant packages, pricing structure and security arrangements. Experienced advisers identify negotiation opportunities that preserve operational freedom whilst managing lender risk concerns. The stable 4% base rate provides a clear reference point for pricing discussions.
-
Finalise funding and maintain communication: Once terms are agreed, ensure transparent ongoing communication with lenders regarding project progress and any material changes. This relationship management supports future flexibility and establishes credibility for subsequent transactions.
Pro Tip: Engaging bespoke funding experts before finalising project plans enables you to structure deals optimally from the outset, securing better terms and preventing costly delays or restructuring.
For investors seeking capital advisory services, partnering with specialists who understand both your objectives and lender requirements streamlines the entire process. Their expertise transforms what could be a complex negotiation into an efficient path to tailored financing.
Discover tailored property finance solutions with James William & Co Capital
Navigating bespoke funding successfully demands expertise in structuring complex property finance and established relationships with specialist lenders. James William & Co Capital brings both, delivering customised financing solutions for sophisticated UK property projects that standard lenders cannot accommodate.

Our specialist property finance approach combines deep market knowledge with a capital concierge service model, providing high-net-worth individuals and institutions a single point of contact for end-to-end structuring, negotiation and execution. Whether you’re managing large-scale acquisitions, ground-up developments or complex refinances, our property finance services deliver rapid, tailored solutions backed by a network of family offices, private credit funds and specialist lenders. Explore our bespoke funding case studies to see how we’ve structured sophisticated financing under tight timelines and demanding conditions.
What is bespoke funding? Frequently asked questions
What kinds of projects benefit most from bespoke funding?
Large-scale developments, mixed-use acquisitions, projects involving offshore structures, and transactions requiring phased funding or unconventional security arrangements benefit most. Bespoke funding excels where standard lending criteria would either decline the opportunity or impose terms that compromise project viability.
How does bespoke funding differ from bridging loans?
Bridging loans are short-term facilities with standardised structures, whilst bespoke funding encompasses fully customised solutions across various terms and structures. Bespoke funding might incorporate bridging elements but extends far beyond into tailored development finance, mezzanine debt and complex capital stacks that bridging products cannot accommodate.
What typical terms might bespoke loans include?
Terms vary enormously based on project specifics but commonly include flexible drawdown schedules, stepped interest rates, tailored covenant packages, bespoke security arrangements and repayment profiles aligned with project cashflows. Negotiation determines exact terms based on project risk and lender appetite.
How long does securing bespoke funding usually take?
Timelines vary from several weeks to a few months depending on project complexity, documentation quality and lender relationships. Established relationships and comprehensive preparation significantly accelerate the process, whilst complex structures requiring detailed due diligence naturally take longer.
Can bespoke funding improve project risk management?
Absolutely. Tailored covenant packages reduce operational constraints compared to rigid standard terms, whilst flexible repayment structures align with project cashflows rather than imposing arbitrary schedules. This alignment reduces financial pressure and enables better project execution. For investors exploring real estate funding sources, bespoke solutions offer superior risk management through customised terms.
Recommended
- James William & Co Capital | Specialist Property Finance
- James William & Co Capital | Specialist Property Finance
- James William & Co Capital | Specialist Property Finance
- James William & Co Capital | Specialist Property Finance
- What Is Bespoke Home Building? Complete Overview
- Bespoke Accounting Support: Transforming Small Businesses
Related Topics
Speak to a specialist
Discuss your finance with James directly
Whole-of-market specialist finance — bridging, development, commercial and residential. No call centres, no obligation. James reviews every enquiry personally.
New to specialist finance? How unbiased broker advice works · Deals we have completed
Explore Related Finance