Published · Updated
gdv sensitivity analysisKnow Your Break Even: GDV Sensitivity for Developers, aligned to RICS
By James Dawes, CeMAP, Founder, James William & Co Capital

GDV sensitivity analysis is the process of varying completed scheme values and other key inputs to find break-even points for land value, profit and lender headroom. It matters because residual appraisals amplify small input changes into large swings in the numbers that decide whether a scheme gets funded. Developers, valuers and lenders all use it, at bid stage, funding stage and mid-scheme, to see how much room there is before a project stops working.
TL;DR:
- Residual appraisals are highly sensitive to small changes in GDV, build costs, and finance rates, which can significantly impact land value and lender headroom.
- Typical ranges for sensitivity testing are around 5% for GDV and 10% for build costs, with wider bands used in uncertain or risky market conditions.
- When residual land value nears unacceptable levels, options include renegotiating land prices, restructuring debt, or reducing scheme scope to maintain viability.
- Sensitivity analysis should be conducted at multiple scheme stages, using consistent base cases and considering combined downside scenarios for more accurate risk assessment.
- Proper interpretation focuses on identifying points where outputs breach thresholds rather than relying solely on base case results, guiding effective decision-making.
Table of Contents
- What GDV is and why sensitivity testing matters to the residual appraisal
- Step-by-step process to run a GDV sensitivity analysis
- Which inputs to vary and what ranges to test
- How to interpret sensitivity outputs and what actions they imply
- Worked example and calculator guidance
- Common real-world uses: funding, bidding, planning viability and mid-scheme reviews
- Practitioner perspective: modelling pitfalls and quality checks
- How James William & Co Capital can help after sensitivity testing
- Primary guidance and standards to consult
- Sources
- FAQ
What GDV is and why sensitivity testing matters to the residual appraisal
Gross development value is the total income a completed scheme generates once every unit is sold, let or valued as an investment. Gov defines it as the sum of:
- Private sale values across the unit mix.
- Affordable housing receipts, whether sold or transferred to a registered provider.
- Commercial or investment value, net of purchaser’s costs.
A residual appraisal works backwards from that figure. Build costs, finance costs, fees and a developer’s profit allowance are deducted from GDV to leave the residual land value, or, where the land price is fixed, the residual profit. That structure is what makes the whole model so sensitive: GDV sits at the top, land value or profit sits at the bottom, and every cost or value assumption in between compounds before it reaches the final line. A modest fall in sales values does not simply shave a modest amount off profit. It can wipe out the residual land value entirely, because profit and land value are usually what is left over once everything else has been paid.
Step-by-step process to run a GDV sensitivity analysis
RICS sets out a process that works for a single site or a portfolio review.
- Evidence unit-by-unit values using comparable transactions, and record the valuation date clearly.
- Build the base residual appraisal with agreed build costs, finance terms, fees and profit allowance.
- Run single-input sensitivities, changing one variable at a time (GDV, build cost, finance rate) while holding the rest static.
- Move to combined scenarios, stressing GDV and cost together to reflect how a downturn actually behaves.
- Capture outputs for each run: residual land value, profit on cost, return on capital, and loan-to-GDV or loan-to-cost headroom.
- Present the results in a clear table so lenders, funders or planning officers can see the base case and downside together.
Pro Tip: Keep the base appraisal locked once sensitivities begin. If you tweak the base case mid-analysis, you lose the ability to compare runs against a single, consistent starting point.
The output of this process is not a single number but a range, and that range is what a lender, a planning officer or a joint venture partner will actually want to see before they commit.
Which inputs to vary and what ranges to test
Not every input deserves the same scrutiny. The variables that move the residual result most are:
- Unit or GDV values, since this sits at the top of the waterfall.
- Build costs, including any allowance for abnormal or unforeseen costs.
- Finance costs, particularly where debt is drawn over a longer period.
- Programme and timing, because a slower sales rate extends the loan term.
Ranges around 5% on GDV and 10% on build costs are typical starting points in practice, with wider ranges applied where there is planning risk, an unproven sales market or abnormal ground conditions; RICS treats sales values, rents and build costs as the core variables to test. Slower sales do more than delay income: they extend the period interest accrues on development debt, which quietly erodes the headroom a sensitivity table shows on paper. Whatever bands are chosen, document why, tying each range to comparable evidence rather than a round number picked for convenience.
How to interpret sensitivity outputs and what actions they imply
A sensitivity table is only useful once it is read as a set of decisions, not a spreadsheet exercise.
- Find the break-even line: the point at which land value, profit or loan-to-GDV headroom hits a level a lender or the developer cannot accept.
- Where the base case sits close to that line, options include renegotiating the land price, trimming specification, phasing delivery to reduce exposure, adding contingency, or restructuring the debt stack with mezzanine or joint venture equity.
- Report the metrics lenders actually watch: loan-to-GDV, loan-to-cost, profit on cost and interest cover, since a scheme that looks fine on profit alone can still breach a covenant on loan-to-GDV once values fall.
The point of running the numbers is to know, before a lender does, exactly where the pressure points sit and what levers are available to relieve them.
Worked example and calculator guidance
Consider a hypothetical example where a development consists of multiple units with an average sale price leading to a base GDV estimate, and build costs are estimated accordingly. Varying GDV down and build costs up within typical sensitivity ranges shows how residual land value can fall sharply, and combined downside scenarios can further reduce land value and approach lender loan-to-GDV limits. This illustration highlights the sensitivity of residual land value to changes in key inputs, though exact figures depend on the specific scheme and market conditions.

Pro Tip: Free tools such as the void cost calculator from Prop-Pocket are useful for testing how sales delays and void periods feed into your finance cost assumptions.
Common real-world uses: funding, bidding, planning viability and mid-scheme reviews
Sensitivity analysis is not a one-off exercise for a single audience. It is expected at several stages of a scheme’s life.
- Lenders use sensitivity outputs to set loan-to-GDV and loan-to-cost limits and to size covenant headroom before drawdown.
- Planning authorities in England expect sensitivity testing as part of financial viability assessments, with GOV.UK’s viability guidance treating alternative scenario testing as standard practice.
- Bidders on land should set their offer ceiling using the downside case, not the base case, and hold contingency back rather than bidding to the optimistic number.
- A mid-scheme reappraisal is worth triggering whenever sales rates slip, build costs move materially, or finance terms are due for renewal.
Each audience reads the same table differently: a lender wants headroom, a planning officer wants proportionality, a bidder wants a ceiling they can defend.
Practitioner perspective: modelling pitfalls and quality checks
The most common mistake is moving one input while leaving correlated ones untouched: a GDV fall usually slows sales, which extends the loan term and raises finance costs, so testing GDV alone understates the damage. Reconcile residual outputs against comparable transactions, state the appraisal date prominently, and bring in an independent valuer or finance structurer once a scheme’s headroom looks thin.
— James William Dawes
How James William & Co Capital can help after sensitivity testing
Sensitivity results that show thin headroom are not a reason to shelve a scheme. They are a reason to revisit how it is funded. Where a downside scenario tightens loan-to-GDV or loan-to-cost limits, restructuring the debt stack, rather than the scheme itself, is often what restores viability. A specialist finance broker can work with developers on exactly this problem, structuring:
- various finance products such as development finance, joint venture equity and mezzanine debt for schemes where the base funding line no longer covers the downside case.
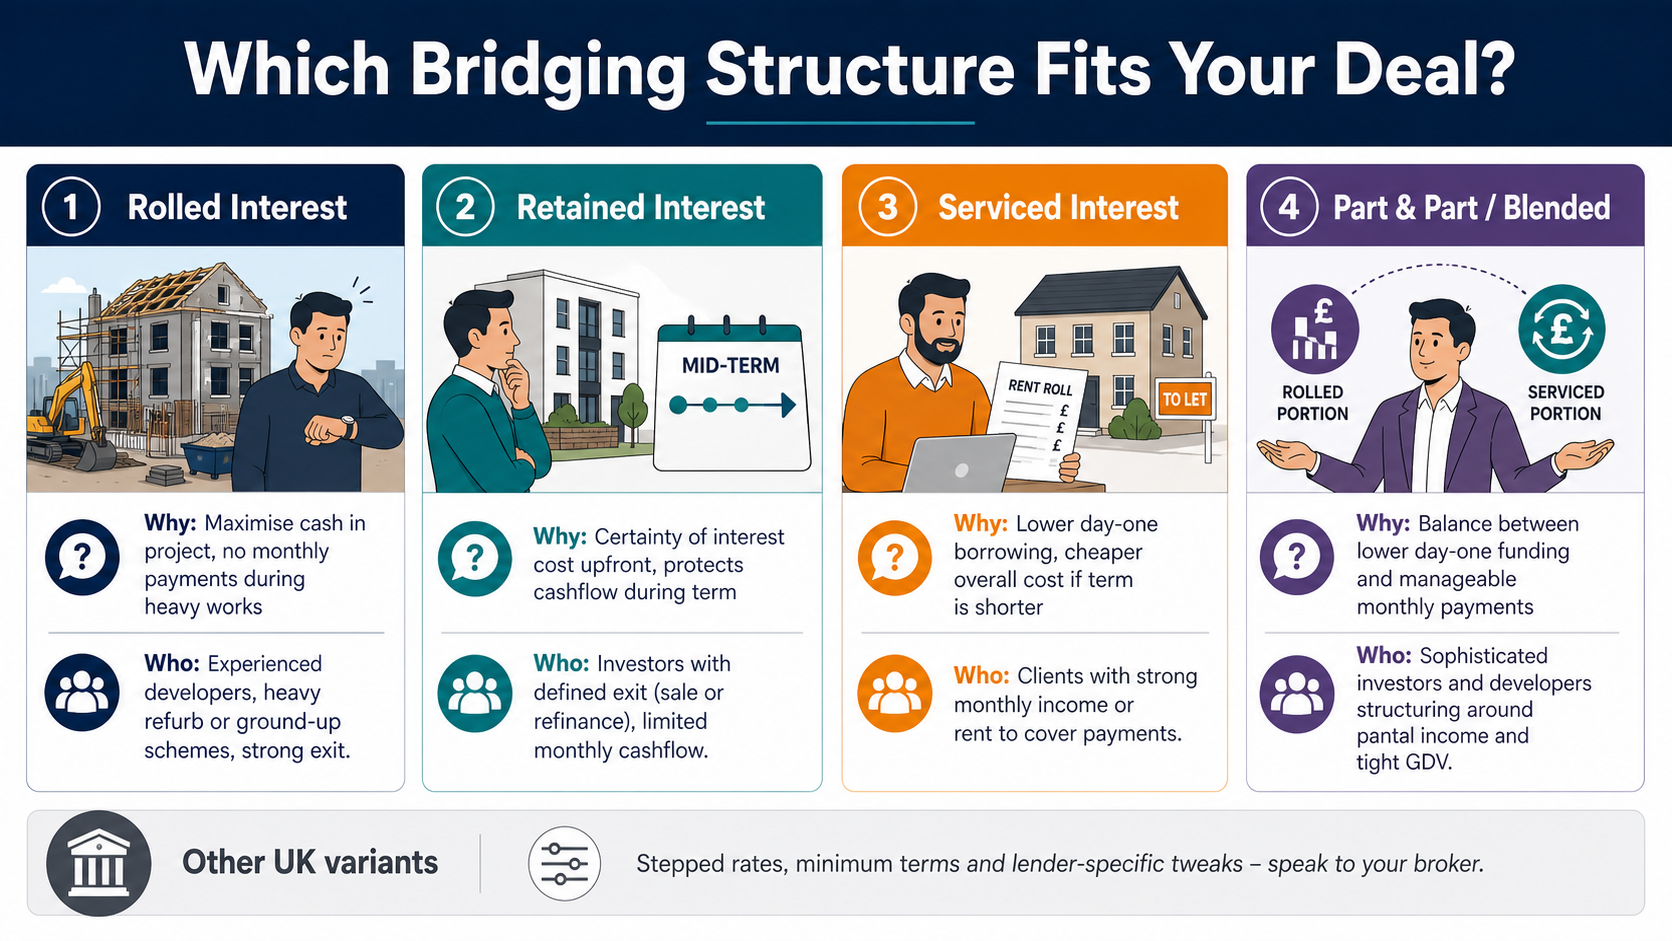
- bridging finance for short-term shortfalls, such as a slower sales period pushing against a facility’s maturity date.
- commercial mortgages for investment exits once a scheme is complete and let.
If your sensitivity analysis has narrowed the margin between your base case and your lender’s limits, an early funding review is worth more than waiting for the market to test it for you. Visit our development finance page to see the structures available.
Primary guidance and standards to consult

For methodology, RICS’s valuation of development property guidance and its viability assessment note under the NPPF are the professional reference points. For planning context, GOV.UK’s viability guidance sets out when sensitivity testing is expected and how alternative scenarios should be presented in a viability report.
Sources
FAQ
How do you interpret sensitivity analysis results?
Read a sensitivity table by finding where residual land value, profit or lender headroom crosses a level you or a funder cannot accept, rather than focusing on the base case alone. A result close to that line signals the need for action such as renegotiating price, adjusting specification or restructuring finance, as RICS recommends testing both single inputs and combined scenarios.
How is GDV calculated?
GDV is the total income a completed scheme would generate, combining private sale values, affordable housing receipts and any commercial or investment value net of purchaser’s costs, as defined by GOV.UK. It sits at the top of a residual appraisal, with costs, finance and profit deducted to reach land value.
What are the three types of sensitivity analysis?
In development appraisal, practice generally distinguishes single-input sensitivity, combined or scenario sensitivity, and break-even sensitivity, which identifies the exact point where an output becomes unacceptable. RICS recommends using single-input testing alongside combined scenarios rather than relying on either alone.
How do I perform a sensitivity analysis?
Start with a documented base residual appraisal, then vary one input at a time such as GDV, build cost or finance rate before testing combined downside scenarios. RICS guidance stresses evidencing unit values, recording the appraisal date and presenting both isolated and combined results clearly for lenders or planning authorities.
Recommended
Related Topics
Speak to a specialist
Discuss your finance with James directly
Whole-of-market specialist finance — bridging, development, commercial and residential. No call centres, no obligation. James reviews every enquiry personally.
New to specialist finance? How unbiased broker advice works · Deals we have completed
Explore Related Finance