
Published · Updated
capital stack real estate5 Ratios UK Lenders Use to Approve a Real Estate Capital Stack
By James Dawes, CeMAP, Founder, James William & Co Capital
The capital stack is the ordered list of funding sources behind a property deal, ranked by who gets paid first and who carries the most risk. Senior debt sits at the bottom and gets repaid before anyone else, which is why it charges the lowest margin. Equity sits at the top, absorbs losses first, and therefore demands the highest return. Every pricing and covenant decision in a deal flows from where you sit in that queue.
TL;DR:
- The lowest-cost senior debt usually advances 60-65% of project cost, with stretch senior increasing that to 85–90% for quicker, simpler funding.
- Mezzanine debt and JV or preferred equity fill funding gaps above senior debt, but each involves trade-offs in legal complexity, control, and profit sharing.
- Lenders run multiple caps simultaneously, with the most restrictive ratio determining the maximum loan, making transparency in the stack crucial for better pricing.
- Arrangement and exit fees, margin adjustments, and profit-sharing terms significantly impact true borrowing costs across the layers.
- Properly structuring the capital stack around the exit, rather than just minimizing headline rates, helps align incentives and reduces risk.
Table of Contents
- How is a real estate capital stack structured layer by layer?
- How do lenders test and price a capital stack?
- Mezzanine, stretch senior or JV equity: which structure fits?
- What does a capital stack actually cost across the layers?
- Which ratios actually decide how much you can borrow?
- How James William & Co Capital assembles and negotiates a stack
- Structure the stack around the exit, not the headline rate
- Sources
- FAQ
How is a real estate capital stack structured layer by layer?
Every layer in the stack trades security for return. The lower you sit, the safer your money and the smaller your reward; the higher you sit, the greater the risk and the bigger the upside you can demand in exchange.
Senior development finance forms the base of most UK development deals. It typically advances around 60–65% of total project cost, sometimes expressed as 50–60% of gross development value (GDV), and it takes a first legal charge over the asset. Because it’s repaid first and secured against bricks and mortar, it carries the cheapest margin in the stack.
Stretch senior is a single facility that pushes beyond a standard senior loan, reaching roughly 85–90% of cost. It removes the need for a second lender entirely, which keeps the security structure simple, but that convenience comes at a meaningfully higher price than blending senior debt with mezzanine.
Mezzanine debt fills the gap between senior debt and equity. It ranks behind the senior lender via a second charge, governed by an intercreditor deed that sets out who controls enforcement and in what order. Mezzanine preserves the developer’s equity contribution but adds legal complexity that stretch senior avoids.
Preferred equity, JV equity and sponsor equity sit at the top. Preferred equity usually carries a priority coupon in the region of 8–12%, paid before ordinary equity sees a penny. JV partners and sponsors take the residual profit, and the residual risk.
| Layer | Typical advance (LTC/LTGDV) | Security | Typical return/pricing |
|---|---|---|---|
| Senior development finance | 60–65% of cost / 50–60% of GDV | First charge | Lowest margin in the stack |
| Stretch senior | Up to 85–90% of cost | First charge (single facility) | Higher margin than senior, no second lender |
| Mezzanine debt | Fills gap above senior | Second charge | Higher than senior, priced for subordinated risk |
| Preferred equity | Balance above debt | Unsecured, priority distribution | Around 8–12% priority coupon |
| Common/JV/sponsor equity | Residual balance | Unsecured, last in line | Residual profit, highest risk |
How do lenders test and price a capital stack?
Lenders don’t lend against a single ratio. They run several caps simultaneously, usually a percentage of total cost and a percentage of gross development value, and the lowest of those figures sets the maximum they’ll advance. That’s the “weakest link” principle: whichever cap is most restrictive wins, regardless of how comfortable the other ratios look.
This matters because two schemes with identical loan-to-cost figures can get very different offers if their GDV assumptions differ. A lender modelling conservative sales values will bind on the GDV cap even when the cost cap looks generous.
Before agreeing terms, most lenders expect:
- A full breakdown of every layer in the stack, including mezzanine or equity terms
- Cost reports, build programmes and sales/rental evidence supporting GDV
- Personal guarantees or debentures where the borrowing entity is thinly capitalised
- Monthly or quarterly drawdown reporting tied to build milestones
Pro Tip: Never present a lender with a partial picture of the stack hoping to fill the gap later. Lenders that discover an undisclosed mezzanine or equity partner mid-process almost always reprice or walk.
Where a lender sits in the hierarchy, not any single headline percentage, is what actually drives pricing and covenants. A senior lender with full visibility of a clean, well-documented stack will typically price tighter and impose lighter covenants than one facing an opaque structure, because transparency directly reduces the lender’s perceived recovery risk.
Mezzanine, stretch senior or JV equity: which structure fits?
Closing a funding gap above senior debt usually comes down to three routes, and each one trades something different away.
- Mezzanine debt suits developers who want to protect their equity contribution and retain full ownership of the profit, provided they can live with an intercreditor deed and a second charge holder in the room. It’s the cheapest way to preserve upside, but it adds a layer of legal negotiation that stretch senior avoids entirely.
- Stretch senior suits schemes where speed and simplicity outweigh cost. A single first-charge facility reaching 85–90% of cost removes the intercreditor negotiation altogether, which can shave weeks off completion, at the price of a higher blended rate than a senior-plus-mezzanine combination.
- JV or preferred equity suits developers with limited cash to put in or who want a partner sharing execution risk. It dilutes profit and hands over some control, but it doesn’t add to the debt burden or require personal guarantees on the same scale.
The underlying decision is really about where you’re willing to concede security, control or profit, not which product looks cheapest on paper.
Pro Tip: Approach senior lenders first to establish the maximum they’ll advance under their binding cap, then size the gap. Only once that gap is known does it make sense to negotiate mezzanine, stretch senior or equity terms, because pricing the gap first often leads to a structure you can’t actually place.
What does a capital stack actually cost across the layers?
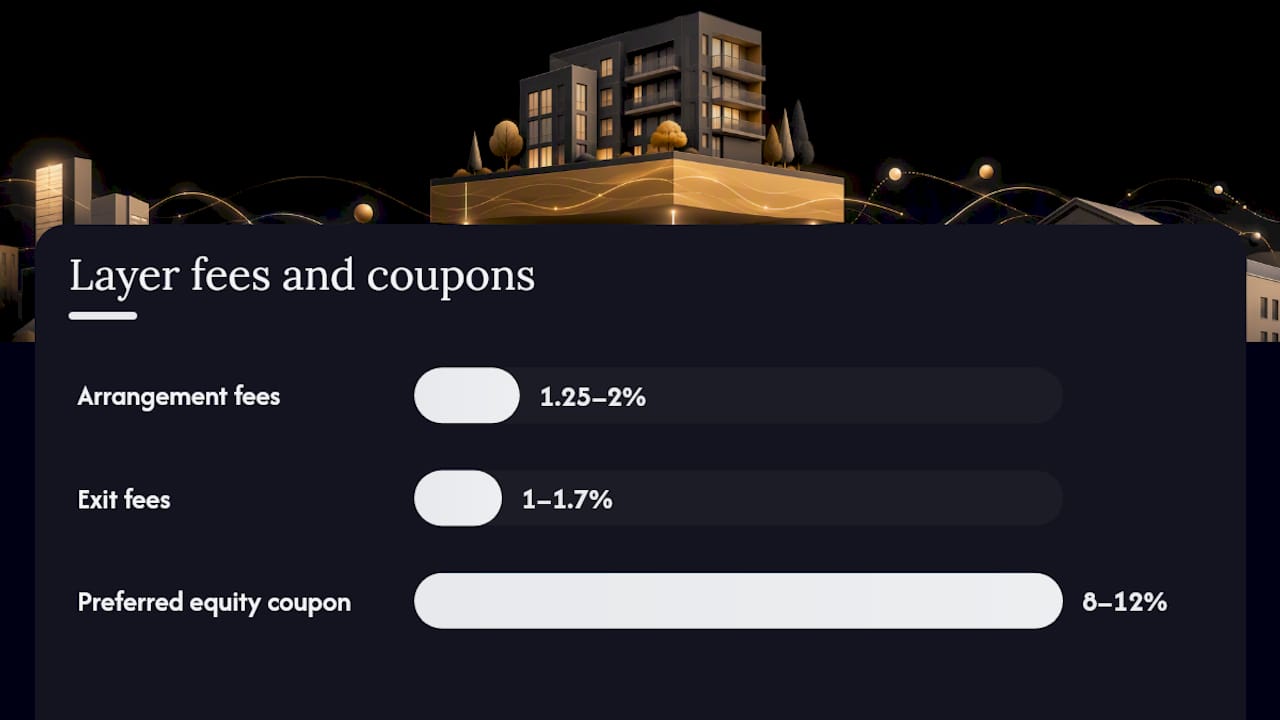
Headline margin tells you almost nothing on its own. Arrangement fees typically run 1.25–2% of the facility, and exit fees add a further 1–1.7%, before legal and monitoring surveyor costs are even counted. On a £5 million facility, that’s potentially £150,000 in fees alone before a single day’s interest accrues.
Preferred equity’s 8–12% coupon can look expensive next to senior debt’s margin, but it’s unsecured capital taking real risk, not a like-for-like comparison. The layers that actually swing an offer’s true cost are:
- Arrangement fees (roughly 1.25–2% of the loan)
- Exit fees (roughly 1–1.7% of the loan)
- Margin over the reference rate, which widens the further up the stack you go
- Preferred-return or profit-share terms on equity layers
The real negotiation levers sit away from headline margin: the size of the developer’s deposit, whether profit share applies above a hurdle, and how the repayment waterfall scopes interest, fees and profit distribution. A smaller equity requirement often costs more in blended terms than a slightly cheaper facility with a larger deposit, which is why comparing offers on margin alone routinely misleads developers.
Which ratios actually decide how much you can borrow?
Five ratios drive every capital-stack model, and developers who only check one of them get caught out.
- Loan-to-value (LTV): loan amount divided by current property value.
- Loan-to-cost (LTC): loan amount divided by total project cost, including build and fees.
- Loan-to-GDV (LTGDV): loan amount divided by the projected gross development value on completion.
- Debt service coverage ratio (DSCR): net operating income divided by debt payments, used mainly on investment and refinance facilities.
- Debt yield: net operating income divided by loan amount, a lender’s sanity check independent of valuation assumptions.
As covered above, lenders run LTC and LTGDV simultaneously and the lower figure binds. Before finalising a stack, run a quick sensitivity check against a GDV fall of 10%, a cost overrun of 10%, and a three to six month build delay. Whichever cap breaks first tells you exactly where your structure is thinnest.
How James William & Co Capital assembles and negotiates a stack
Assembling a multi-layered stack under time pressure is where a specialist broker earns its fee. Some specialist brokers work as a capital concierge, offering developers, investors and asset managers a single point of contact across senior lenders, mezzanine providers, family offices and JV equity partners, rather than negotiating each relationship in isolation.
Sequencing matters more than most developers expect:
- Approach senior or stretch senior lenders first to establish the binding cap
- Size the residual gap before approaching mezzanine or equity providers
- Prepare cost reports, build programmes and sales evidence before the first lender conversation, not after
- Keep the full stack visible to every party from the outset
Pro Tip: Turnaround expectations vary sharply by complexity. A straightforward senior refinance can complete in weeks; a four-layer stack with offshore vehicles and bespoke covenants needs months of lead time. Build that into your acquisition timeline early.
Structure the stack around the exit, not the headline rate
The strongest capital stacks aren’t the cheapest on paper. They’re the ones where every layer’s incentives point toward the same exit, and where the sponsor hasn’t over-leveraged chasing a lower blended rate at the cost of covenant flexibility.
— James William Dawes
Sources
- Development Finance Costs: The Capital Stack Explained - In Partnership with Brickflow
- Property development finance: senior debt, mezzanine and equity
- The Capital Stack, layer by layer: How a UK development deal gets funded in 2026
- Capital Stack Explained: Risk, Return & Funding Positioning
FAQ
Is capital stacking a legitimate way to fund a deal?
Yes. Capital stacking is standard practice in UK property finance, used by lenders and developers alike to allocate risk and return transparently across senior debt, mezzanine and equity layers.
How does a lender decide where they’ll sit in the stack?
Lenders assess your existing and proposed layers, then test their advance against multiple caps such as loan-to-cost and loan-to-GDV, lending against whichever cap is most restrictive.
Is mezzanine debt or JV equity better for filling a funding gap?
Mezzanine preserves your equity and profit but adds intercreditor complexity through a second charge; JV equity dilutes profit and control but avoids extra debt and personal guarantees, so the right choice depends on how much dilution you can accept.
What creates most property wealth: leverage or long-term holding?
Most property wealth builds through disciplined use of leverage combined with patient, long-term ownership rather than short-term speculation, which is why structuring the capital stack correctly at the outset matters so much.
Who arranges multi-layered capital stacks for UK developers?
Specialist brokers such as James William & Co Capital coordinate senior lenders, mezzanine providers and equity partners through a single point of contact, which is central to how they structure development finance for complex UK deals. Readers exploring wealth planning alongside a live acquisition can also review how capital-stack decisions interact with broader HNW structuring, or start with James William & Co Capital’s full service overview.
Recommended
Related Topics
Speak to a specialist
Discuss your finance with James directly
Whole-of-market specialist finance — bridging, development, commercial and residential. No call centres, no obligation. James reviews every enquiry personally.
New to specialist finance? How unbiased broker advice works · Deals we have completed
Explore Related Finance