
Published · Updated
portfolio buy to let ltd companyA portfolio buy to let ltd company works best for higher-rate landlords
By James Dawes, CeMAP, Founder, James William & Co Capital
A portfolio buy to let ltd company tends to pay off if you’re a higher or additional-rate taxpayer with significant mortgage borrowing, and you plan to reinvest most of your rental profit rather than draw it out as income. For anyone in that position, corporation tax at 19% or 25% on full interest deduction usually beats personal tax rates squeezed by Section 24.
The trade-offs are real, though, and they cut the other way for some landlords:
- Extraction tax bites back. Pulling profit out as dividends or salary adds a second tax layer, which can erase some of the corporation tax saving.
- Moving existing property in is expensive. Capital gains tax and stamp duty land tax apply as if you’d sold the properties to a stranger. This often runs into tens of thousands of pounds.
- Company mortgages cost more. Deposits sit around 25%, rates carry a premium, and the lender pool is narrower.
Pro Tip: Before you commit to anything, model your own numbers rather than trusting a rule of thumb. What works for a landlord with two mortgage-free flats can be the wrong answer for someone with eight highly geared terraces. If your numbers are close to the tipping point, brief a property tax specialist and a broker who understands SPV lending before you file anything with Companies House.
Key Takeaways
Incorporating a buy to let portfolio tends to reward higher-rate, heavily geared landlords who retain profit, but the mortgage premium and transfer costs can erase that advantage without careful modelling.
| Point | Details |
|---|---|
| Retained profit favours companies | Corporation tax at 19% to 25% with full interest deduction usually beats Section 24’s 20% basic-rate credit for higher-rate taxpayers. |
| Extraction narrows the gap | Dividend or salary tax on money drawn from the company adds a second tax layer that can offset much of the saving. |
| Transfers trigger real bills | Moving existing property into a company means CGT at 18% or 24% plus SDLT with the 5% surcharge, calculated at market value. |
| Company mortgages cost more | Expect roughly 25% deposits, a rate premium, and personal guarantees from every director. |
| A hybrid approach often wins | Keeping existing holdings personal and buying new purchases through a company captures most of the benefit without the transfer bill. |
| Refinancing needs specialist structuring | James William & Co Capital arranges equity release and multi-layer debt stacks so growing portfolios can recycle capital between purchases. |
Table of Contents
- What is a buy to let limited company and how does it work?
- How does Section 24 change the maths for a company?
- What does it cost to transfer existing properties into a company?
- How do company buy to let mortgages differ from personal ones?
- Single SPV or multiple companies: which structure fits a growing portfolio?
- What is the practical checklist before incorporating a portfolio?
- How do specialist brokers structure finance for company-held portfolios?
- Does a limited company actually protect your personal assets?
- Company or personal ownership: which suits a long-term exit strategy?
- Could future tax reform change the case for incorporating?
- Editorial take: what the modelling actually shows
- Get specialist help structuring your portfolio company’s finance
- Sources
- FAQ
What is a buy to let limited company and how does it work?
A special purpose vehicle, or SPV, is simply a limited company set up to hold and let residential property rather than trade in goods or services. The company, not you personally, owns the properties, signs the mortgages, and collects the rent. You own shares in the company instead of bricks and mortar directly, and that distinction sits at the heart of every tax and lending difference discussed later in this article.
Setting up a property company starts at Companies House, where you register the business, appoint at least one director, and choose a Standard Industrial Classification (SIC) code that describes what the company does. For buy-to-let, the relevant codes are usually 68100 (buying and selling own real estate), 68201 (renting and operating own or leased residential property), 68209 (other letting and operating of own or leased real estate), or 68320 (management of real estate on a fee or contract basis). Lenders pay close attention to these codes: a clean, property-only SIC list makes underwriting simpler and widens your choice of finance.
Running the company brings ongoing obligations that a personal landlord never has to think about:
- Annual company accounts filed with Companies House
- A CT600 corporation tax return filed with HMRC each year
- A confirmation statement confirming the company’s details are current
- A dedicated business bank account, kept separate from personal finances
The cash flow itself is straightforward once the structure is in place. Rent lands in the company account, the company pays mortgage interest, insurance, repairs, letting agent fees and any other running costs, and whatever remains is profit, taxed at the corporation tax rate before you decide whether to leave it in the business or extract it.
How does Section 24 change the maths for a company?
Section 24 stopped personal landlords from deducting mortgage interest as an expense against rental income; instead, they get a 20% basic-rate tax credit on those finance costs, regardless of what rate of tax they actually pay. A higher-rate taxpayer effectively loses tax relief on a chunk of their interest bill, which is why so many portfolio landlords started looking at incorporation once the change bedded in around 2020.
Companies were never touched by Section 24 because they don’t pay income tax on rental profit at all. Corporation tax rates sit at 19% on profits under £50,000 and 25% on profits over £250,000, with marginal relief tapering the rate in between, and crucially, a company deducts its full mortgage interest before that tax is calculated. That gap between a 20% tax credit and full deductibility widens the further into higher-rate territory you sit, which makes the corporate route increasingly attractive for heavily mortgaged, higher-rate landlords.
The catch is what happens when you want the money in your own pocket. A company’s profit gets taxed twice on its way to you as personal income:
- Corporation tax takes 19% to 25% off the profit inside the company.
- Dividend tax or PAYE then applies when you extract what’s left, at your personal marginal rate.
- Employer’s National Insurance adds a further layer if you take the money as salary rather than dividends.
This is where the “double taxation” argument against companies comes from, and it’s a fair one if you need the income to live on. A personal landlord paying 40% tax on rental profit, uncomfortable as that is, only pays tax once.
Here’s a simplified example to show how it plays out. Say a portfolio generates £40,000 of rental profit before finance costs, with £15,000 of mortgage interest.
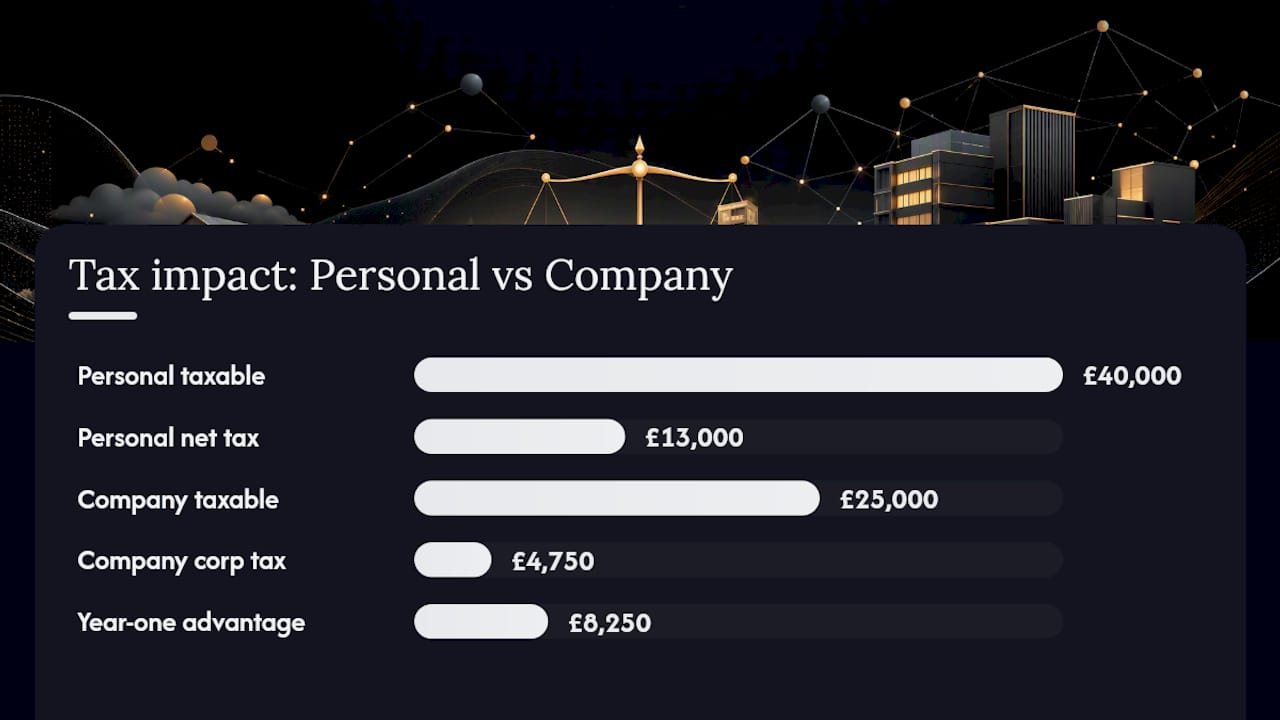
A personal higher-rate landlord pays 40% tax on the full £40,000 rental profit (interest no longer reduces the taxable figure), then claims back a 20% credit on the £15,000 interest. Roughly £16,000 tax, minus a £3,000 credit, leaves about £13,000 net tax and £12,000 in their pocket after interest.
A company earning the same £40,000, less the fully deductible £15,000 interest, pays corporation tax on £25,000 profit. Leave it there to fund the next deposit, and the company is roughly £8,000 better off than the personal landlord in year one alone. Extract that £20,250 as a dividend, though, and dividend tax at the landlord’s marginal rate closes much of that gap. Retained, reinvested profit is where the company structure earns its keep. Extracted income is where the advantage often narrows to nothing.
What does it cost to transfer existing properties into a company?
Moving a property you already own into a limited company you also own doesn’t dodge tax, because HMRC treats you and “your” company as connected parties. The transfer is deemed a disposal at market value for capital gains tax purposes and a purchase at market value for stamp duty land tax, even though no cash changes hands between you and a third party.
That triggers two separate bills:
- Capital gains tax at 18% or 24% on residential property gains, calculated on the difference between what you paid and today’s market value.
- Stamp duty land tax, charged at standard residential rates plus the 5% additional dwelling surcharge, calculated on the property’s current market value regardless of the price you originally paid.
- ATED (Annual Tax on Enveloped Dwellings) can apply where a dwelling held by a company is worth more than £500,000, though most portfolio buy-to-lets qualify for relief because they’re genuinely let out commercially rather than used privately.
Two reliefs get mentioned constantly in this space, and both are narrower than landlords hope.
Section 162 incorporation relief can roll a capital gain into the value of the shares you receive, deferring the CGT bill rather than eliminating it, but only if HMRC accepts that you’re running a genuine property business, not simply holding investments. The “business” test looks at time spent, the range of activities beyond just collecting rent, and whether you’re actively managing the portfolio. HMRC has challenged claims where landlords with a handful of properties and a managing agent tried to claim relief, so treat any claim of Section 162 relief as needing specialist tax advice before you rely on it.
Partnership incorporation relief for SDLT works on a similar principle but applies only where the properties were genuinely held in a formal partnership before the transfer, not simply owned jointly by spouses or family members. HMRC scrutinises these claims closely, and the relief tapers depending on the transferring partner’s continuing interest in the company.
Pro Tip: Get a market valuation and a specialist tax opinion on Section 162 eligibility before you transfer a single property. The paperwork trail matters more than the intention if HMRC ever asks questions later.
How do company buy to let mortgages differ from personal ones?
SPV lending works differently because the company, not you, is the borrower on paper, even though lenders look straight through to the directors’ experience, income and credit history to decide whether to say yes. Most lenders want a deposit of around 25% for company borrowers, and personal guarantees from directors are close to universal, meaning the “limited” in limited company offers less protection against the mortgage debt than many landlords assume.
The lender panel narrows considerably compared with personal buy-to-let. Fewer high street names lend to SPVs, pushing most portfolio landlords towards specialist and challenger lenders who understand property-only SIC codes and multi-property portfolios.
| Factor | Personal buy-to-let mortgage | Company (SPV) buy-to-let mortgage |
|---|---|---|
| Typical deposit | 20% to 25% | Around 25% or more, especially for a newly formed company |
| Rate premium | Baseline market rate | Often carries a rate premium above equivalent personal rates |
| Lender pool | Wide, including most high street banks | Narrower, dominated by specialist and challenger lenders |
| Personal guarantee | Not applicable | Almost always required from directors |
| Underwriting focus | Personal income and credit history | Director track record, company accounts, portfolio experience |
That rate premium and the higher arrangement fees that usually accompany company products are the single biggest thing that erodes the tax advantage on paper. Even a modest rate uplift on a typical mortgage costs several thousand pounds annually, which needs weighing against whatever corporation tax saving you’re expecting.
Refinancing inside a company is where the structure earns its stripes for growth-focused investors, because releasing equity through a remortgage is not a disposal and doesn’t trigger a CGT event the way selling would. Recycling capital this way lets a portfolio landlord fund a deposit on the next purchase without ever selling an existing asset, provided the lender’s interest cover ratio stress test at a notional rate still leaves room. Our guide to complex refinance for UK property investors covers the negotiation tactics that keep this process moving when lenders get cautious about aggregate exposure across a growing portfolio.
Expect lenders to ask for a fuller documentation set than a personal application: certificate of incorporation, memorandum and articles of association, at least one or two years of company bank statements where the company has traded, and evidence of the directors’ property or business experience. Our guide to loan to value calculations is worth reading alongside this if you’re not familiar with how LTV interacts with deposit requirements on SPV products specifically.
Single SPV or multiple companies: which structure fits a growing portfolio?
Most landlords start with one SPV and only think about splitting it once the portfolio grows past a handful of properties. A single company is cheaper to run: one set of annual accounts, one CT600, one confirmation statement, and one relationship to manage with an accountant.
The case for multiple SPVs, or a holding company with subsidiaries underneath it, usually comes down to risk and exit planning rather than tax:
- Ring-fencing limits your exposure if one property or one lender relationship runs into trouble, since liabilities in one SPV don’t automatically touch assets in another.
- Cleaner exits are possible when a buyer can purchase shares in a single-property SPV rather than the property itself, which can sometimes reduce the buyer’s own SDLT exposure and simplify the sale.
- Family and succession planning often favours a holding structure, where shares in subsidiary companies can be passed down or restructured without disturbing the underlying properties or their mortgages.
- External investors joining a portfolio usually prefer a holding company arrangement that separates their equity stake from operational risk in any one SPV.
Lenders don’t always love complexity, though. Many look at your total exposure across every company you control, and cross-guarantees between linked SPVs are common, so splitting a portfolio into multiple companies doesn’t always insulate you from a lender’s perspective the way it might on paper.
What is the practical checklist before incorporating a portfolio?
Work through this in order rather than jumping straight to “should I incorporate”, because the answer depends entirely on inputs specific to your portfolio.
- Gather your numbers. Current tax band, total mortgage interest paid annually, loan-to-value on each property, and an honest estimate of unrealised capital gains on anything you’d be transferring.
- Establish your SDLT exposure. Calculate what stamp duty land tax and CGT would actually cost if you moved existing properties in, including the 5% additional dwelling surcharge.
- Decide your extraction plan. Will you need to draw most of the rental profit as income, or can you leave the bulk of it retained inside the company to fund growth?
- Model the mortgage premium. Get indicative rate and fee quotes for SPV lending against your current personal rates, and don’t assume the tax saving automatically outweighs the cost.
- Run a sensitivity check. Test your numbers over a five and ten-year holding period, and against a scenario where you need to extract more income than planned, such as after retirement.
A pragmatic middle ground that comes up repeatedly among property tax specialists: leave your existing holdings in your own name and buy every new property through a company. That captures most of the corporate tax advantage on future growth without the upfront CGT and SDLT bill of moving what you already own.
Pro Tip: Instruct a property-specialist accountant and a broker who works regularly with SPV lenders before you form the company, not after. Getting the SIC code, share structure and lender relationship right from day one saves a rework further down the line.
How do specialist brokers structure finance for company-held portfolios?
Arranging finance for a company-held portfolio rarely looks like a single mortgage application, particularly once a landlord is running several SPVs, has cross-guarantees in place, or wants to layer in mezzanine funding alongside a senior mortgage to stretch further on the next acquisition. James William & Co Capital works as a capital concierge for exactly this kind of complexity: one point of contact who selects the right lender from a panel of specialist and challenger banks, private credit funds and family offices, then negotiates the covenant package around what the portfolio can actually support.
A typical refinance path looks like this:
- Review the SPV’s existing mortgages, rental income and interest cover across the whole portfolio, not property by property.
- Identify which properties hold enough equity to release without breaching a lender’s aggregate exposure limits.
- Structure the refinance, often alongside bridging or mezzanine debt, to fund the deposit on the next acquisition without a disposal.
- Negotiate covenants that account for offshore ownership vehicles or family trust structures where these sit above the SPV.
Offshore vehicles and bespoke covenant packages come up often with clients who’ve built a portfolio across multiple companies or jurisdictions, and these are exactly the situations where a generalist mortgage adviser tends to hit a wall.
A portfolio landlord’s growth speed is usually limited by how quickly equity can be recycled, not by how much new deposit money they can save. Structuring the refinance correctly is often the single biggest lever on how fast a company-held portfolio can scale.
Read our guide to real estate funding sources for UK developers for a broader look at how these funding layers fit together across a growing portfolio.
Does a limited company actually protect your personal assets?
Limited liability is the theory behind incorporating, and it’s genuinely true in one specific sense: if the company is sued or falls into unrelated debt, your personal assets outside the company are generally protected. That protection is narrower in practice than most first-time incorporators expect.
Mortgage lenders almost universally require personal guarantees from directors on SPV lending, which means if the company defaults, the lender can still pursue you personally for the shortfall. The limited liability shield protects you from most third-party claims, tenant disputes or contractor litigation, but it does very little against the mortgage debt itself, which is usually the largest liability in a property portfolio by far.
Where the structure does add real protection is against claims unrelated to the mortgage: a tenant injury claim, a contractual dispute with a letting agent, or liability arising from one property in the portfolio. Holding properties through separate SPVs, discussed earlier, sharpens this further by containing a claim against one property to that specific company rather than exposing the whole portfolio.
The asset protection case for incorporating is real, but it’s a second-order benefit behind the tax mechanics. Anyone incorporating purely for liability reasons, without the tax and financing numbers supporting the move, is usually better served by adequate insurance and a well-drafted tenancy agreement.
Company or personal ownership: which suits a long-term exit strategy?
The long-term picture looks different depending on how you expect to exit. A personal landlord who sells a property pays capital gains tax once, on the increase in value since purchase, and that’s the end of it. Exiting a company-held portfolio is more complicated because the value sits inside shares, not directly in the properties.
Selling the company itself, rather than the individual properties, can suit a buyer who wants to acquire an established portfolio with existing tenancies and financing in place, and a share sale sometimes carries lower SDLT for that buyer than buying the properties directly. That can make company-held portfolios genuinely more attractive to certain buyers, particularly other investors or funds looking to scale quickly.
Extracting value from a company on exit still runs through dividend or liquidation tax rules, though, which adds a layer that a personal sale simply doesn’t have. Winding up a company to release final profits triggers its own tax treatment, and the numbers need modelling specifically for your situation rather than assumed.
For succession planning, company ownership offers something personal ownership can’t: shares can be gifted or restructured across family members gradually, potentially spreading value without the all-or-nothing disposal that transferring a personally owned property involves. This is one of the strongest long-term arguments for a holding structure where the exit plan includes passing the portfolio to the next generation rather than selling to a third party.
Could future tax reform change the case for incorporating?
Property tax rules have moved often enough over the past decade that anyone building a portfolio company today should plan for further change rather than assume the current rules are fixed. Section 24 itself was phased in gradually rather than introduced overnight, and corporation tax rates have shifted more than once in recent years, most recently with the introduction of the 25% band on profits over £250,000 alongside marginal relief for amounts in between.
The specific risk for portfolio companies is less about corporation tax rates moving again and more about whether the extraction side gets tightened. Dividend tax allowances have been cut repeatedly in recent years, and there’s no guarantee that trend stops, which would directly narrow the retained-profit advantage that makes incorporation attractive in the first place.
There’s also a live question around whether reliefs like Section 162 incorporation relief face tighter interpretation. HMRC’s scrutiny of the “business” test has increased rather than relaxed, and any landlord relying on that relief for a future transfer should treat today’s guidance as a snapshot rather than a permanent rule.
None of this argues against incorporating. It argues for modelling your decision with enough margin that a modest tightening of dividend tax or a small corporation tax movement doesn’t flip the answer, and for revisiting the calculation every couple of years rather than treating incorporation as a one-off decision made in isolation.
Editorial take: what the modelling actually shows
Most guidance on this topic treats incorporation as a binary decision, tax efficient or not, when the real answer sits in the financing mechanics that get far less attention. The gap between personal and company tax treatment is genuinely wide for a heavily geared higher-rate landlord retaining profit, but that gap closes fast the moment extraction or a company mortgage premium enters the picture. Anyone modelling this on tax alone, without pricing the SPV rate uplift and arrangement fees against a real lender quote, is working from half the picture.
What gets underestimated is refinancing capacity. A company structure that lets you recycle equity without triggering a disposal is often worth more to a growing portfolio than the corporation tax saving itself, because it’s the lever that determines how fast you can scale at all. Prioritise getting indicative lender terms and a genuine tax comparison before you touch Companies House. The paperwork is the easy part.
— James William Dawes
Get specialist help structuring your portfolio company’s finance
James William & Co Capital exists for exactly the moment this article leads to: once the tax case for incorporating a portfolio buy to let ltd company stacks up, the harder problem becomes finding lenders who actually want to fund it on sensible terms. Where a generalist broker sees one SPV mortgage application, we see a debt structure that can layer senior lending, mezzanine finance and equity recycling to keep a portfolio growing without stalling at a single lender’s exposure limit.

That matters most when you’re refinancing an existing SPV to release equity for the next purchase, or juggling cross-guarantees across multiple companies, situations where a narrow high street lending criteria simply says no. As a capital concierge working with specialist lenders, private credit funds and family offices, James William & Co Capital structures the covenant package around what your portfolio can genuinely support, not what a standard product allows. If you’re weighing up incorporation and want to know what your portfolio can actually borrow against, get in touch with our specialist property finance team in London to talk through your numbers before you commit to a structure.
Sources
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Should I put my buy-to-let properties in a limited company?
It depends on your tax band, gearing and extraction plans: a heavily mortgaged higher-rate taxpayer retaining profit often benefits, while a lower-rate landlord who needs the income to live on may not. Model the transfer costs and mortgage premium against the tax saving before deciding.
How do I start a buy-to-let portfolio through a company?
Register the company at Companies House with a property-focused SIC code, open a dedicated business bank account, and secure indicative SPV mortgage terms from a specialist lender before committing to your first purchase. Working with a broker experienced in company-held portfolios, such as James William & Co Capital, helps avoid the narrower lender pool catching you out on your first deal.
Recommended
Related Topics
Speak to a specialist
Discuss your finance with James directly
Whole-of-market specialist finance — bridging, development, commercial and residential. No call centres, no obligation. James reviews every enquiry personally.
New to specialist finance? How unbiased broker advice works · Deals we have completed
Explore Related Finance